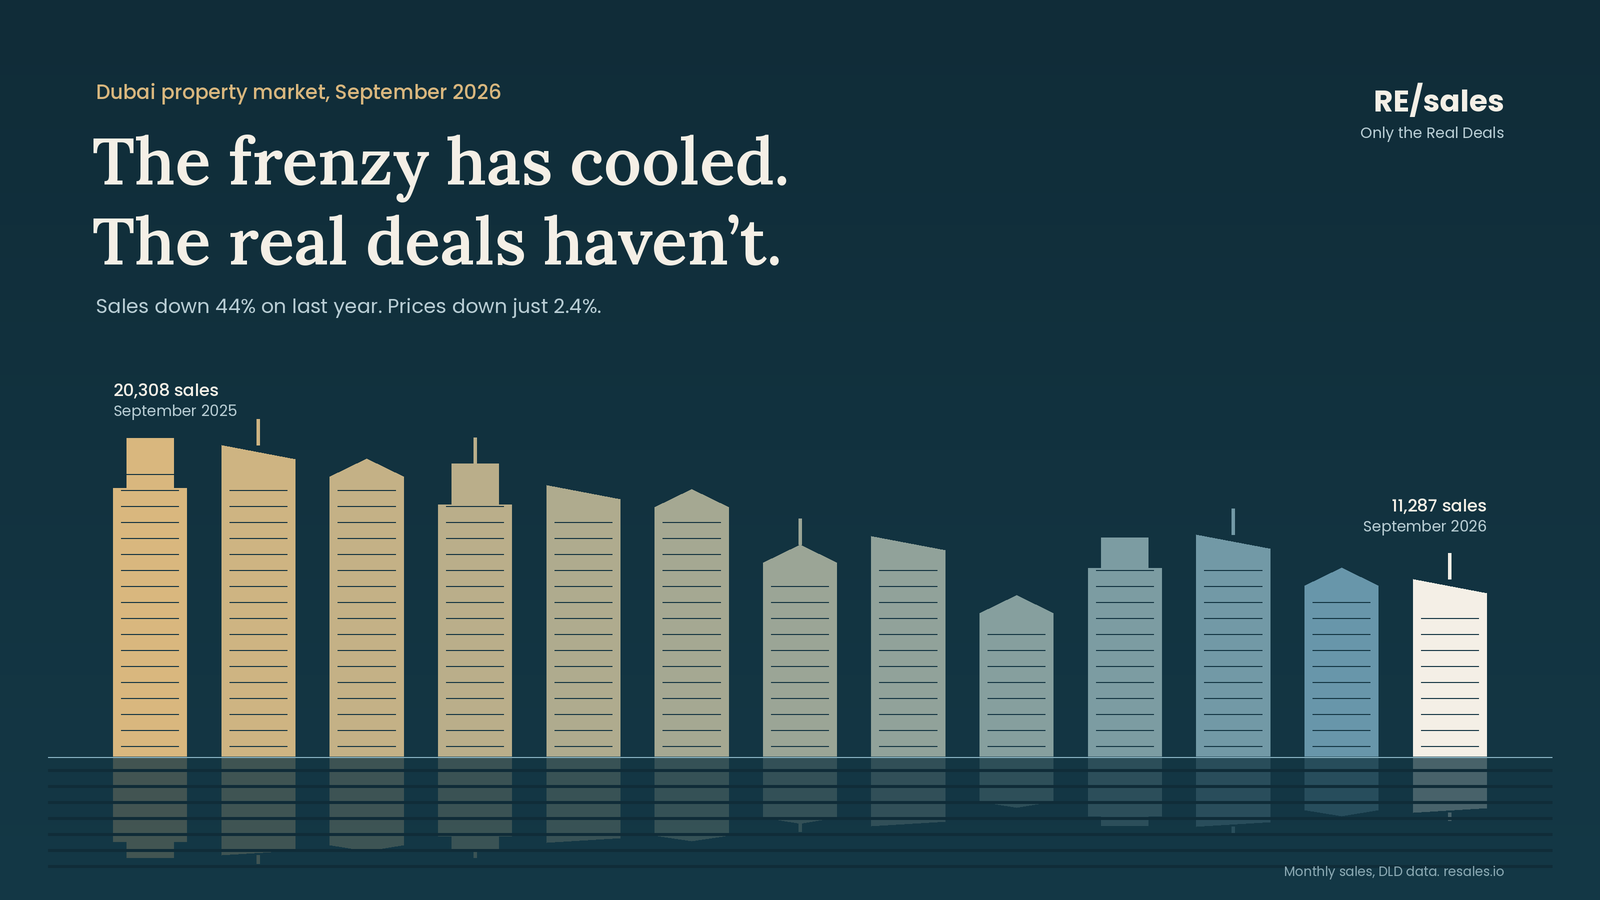
September's DLD numbers confirm what buyers on the ground already feel: Dubai is no longer a market where anything sells at any price. Deal volume has dropped sharply from last year's peak, off-plan has cooled the most, and thousands of new units are being handed over every month. That is exactly why Dubai has become a better market to buy in — if you know where to look.
September 2026 at a glance
Indicator | September 2026 | vs September 2025 |
|---|---|---|
Sales transactions | 11,430 | ≈ −44% |
Sales value | AED 29.66 bn | ≈ −46% |
All transactions (incl. mortgages & gifts) | 16,490 / AED 50.78 bn | — |
Off-plan sales | 7,476 deals / AED 13.63 bn | — |
Ready sales | 3,955 deals / AED 16.03 bn | — |
Average price per sq ft (all sales) | AED 1,654 | −2.4% |
January–September 2026 total | AED 574.12 bn | 2nd-highest ever |
What the numbers are really saying
1. Volume halved — prices did not collapse. Dubai recorded roughly 44% fewer sales than in September 2025, yet the average price per square foot is only about 2.4% lower year on year, and around 9% below this year's April peak of AED 1,822. Most owners are holding their price. The ones who need to sell are pricing to move — and those are the units worth finding.
2. Off-plan cooled the most. Off-plan apartment deals fell by more than half year on year, the median off-plan apartment ticket dropped about 12% to AED 1.14 million, and off-plan price per sq ft slipped around 5%. Ready (resale) apartments held up far better: deals were down about 25%, while price per sq ft rose around 2% to AED 1,520 and the median resale apartment traded at AED 1.25 million.
3. Ready property is now the cheaper way into Dubai. New-launch apartments averaged about AED 1,703 per sq ft in September; ready resale apartments averaged about AED 1,520. That is a gap of roughly 11% — and a ready unit starts earning rent from the day of transfer, with no construction or handover risk.
4. Ready stock carries the money. Ready sales were only 35% of deals but 54% of total sales value. Serious capital — end-users and long-term landlords — is going into finished homes.
5. The handover wave is here. In September alone, 19 projects with 4,723 units were completed, while another 21 projects with 4,695 units were launched. More supply is reaching the rental market: new apartment leases rose about 24% year on year, while the median new apartment rent eased about 4% to AED 70,000. Investors who bought off-plan in 2022–2023 expecting a quick flip now face final payments and a tenant's market — and many of them are ready to exit at, or even below, their original purchase price.
Independent indices point the same way. ValuStrat's August reading showed Dubai residential values down 3.1% year on year (apartments −5.3%, villas −1.7%, the villa segment's first annual decline since 2021), while Knight Frank's prime index was still up 10.9% to June. Dubai is no longer one market: the prime end is holding, the mainstream is adjusting.
Where buyers were active
On the resale side, the most transactions in September were recorded in Jumeirah Village Circle, Business Bay and Dubai Marina. By value, resale money concentrated in Mohammed Bin Rashid City (Dubai Hills area), Palm Jumeirah, Dubai Marina and Downtown Dubai. On the primary side, Dubai South, Dubai Creek Harbour and Business Bay led the month.
Why this is a buyer's window
A slower market does not mean fewer opportunities — it means fewer obvious ones. In 2023 almost everything went up, so the average was good enough. In late 2026 the average is flat, and the return comes from the specific unit: the right building, the right price against recent DLD sales, and a seller with a real reason to move.
Those sellers exist today in three clear groups: off-plan investors close to handover who don't want to pay the final instalments; owners of ready units competing with brand-new supply next door; and developers holding completed but unsold stock who are open to negotiation on price or payment terms.
How resales.io finds the real deals
Every opportunity on resales.io is checked against hard data before it is published: recent DLD transactions in the same building and community; the asking price against the original launch price and against comparable ready units; rental yield based on actual registered tenancy contracts; the official developer handover date; and the payment plan still outstanding.
What makes the cut: near-completion resales at or below launch price, ready apartments priced below new launches in the same area, and completed developer stock with genuinely negotiable terms. If the numbers don't work, it doesn't go on the site.
See this week's opportunities
The market has cooled. The deals are still there — they just have to be found.
resales.io — Only the Real Deals.
Find Your Deal Faster → Browse this week's Opportunities on resales.io.
Sell Your Property Faster → Talk to us about listing your Dubai property with resales.io.
Sources: Dubai Land Department transaction data (sales, price per sq ft, rents, supply and year-on-year comparisons via DXBinteract); DLD monthly totals as published by Emirates 24|7 on 1 October 2026; ValuStrat Price Index (August 2026) and Knight Frank Prime Global Cities Index (to June 2026) as reported by Dubai Chronicle. Year-on-year changes are resales.io calculations. Figures may be revised by DLD. This note is market information, not investment advice.